


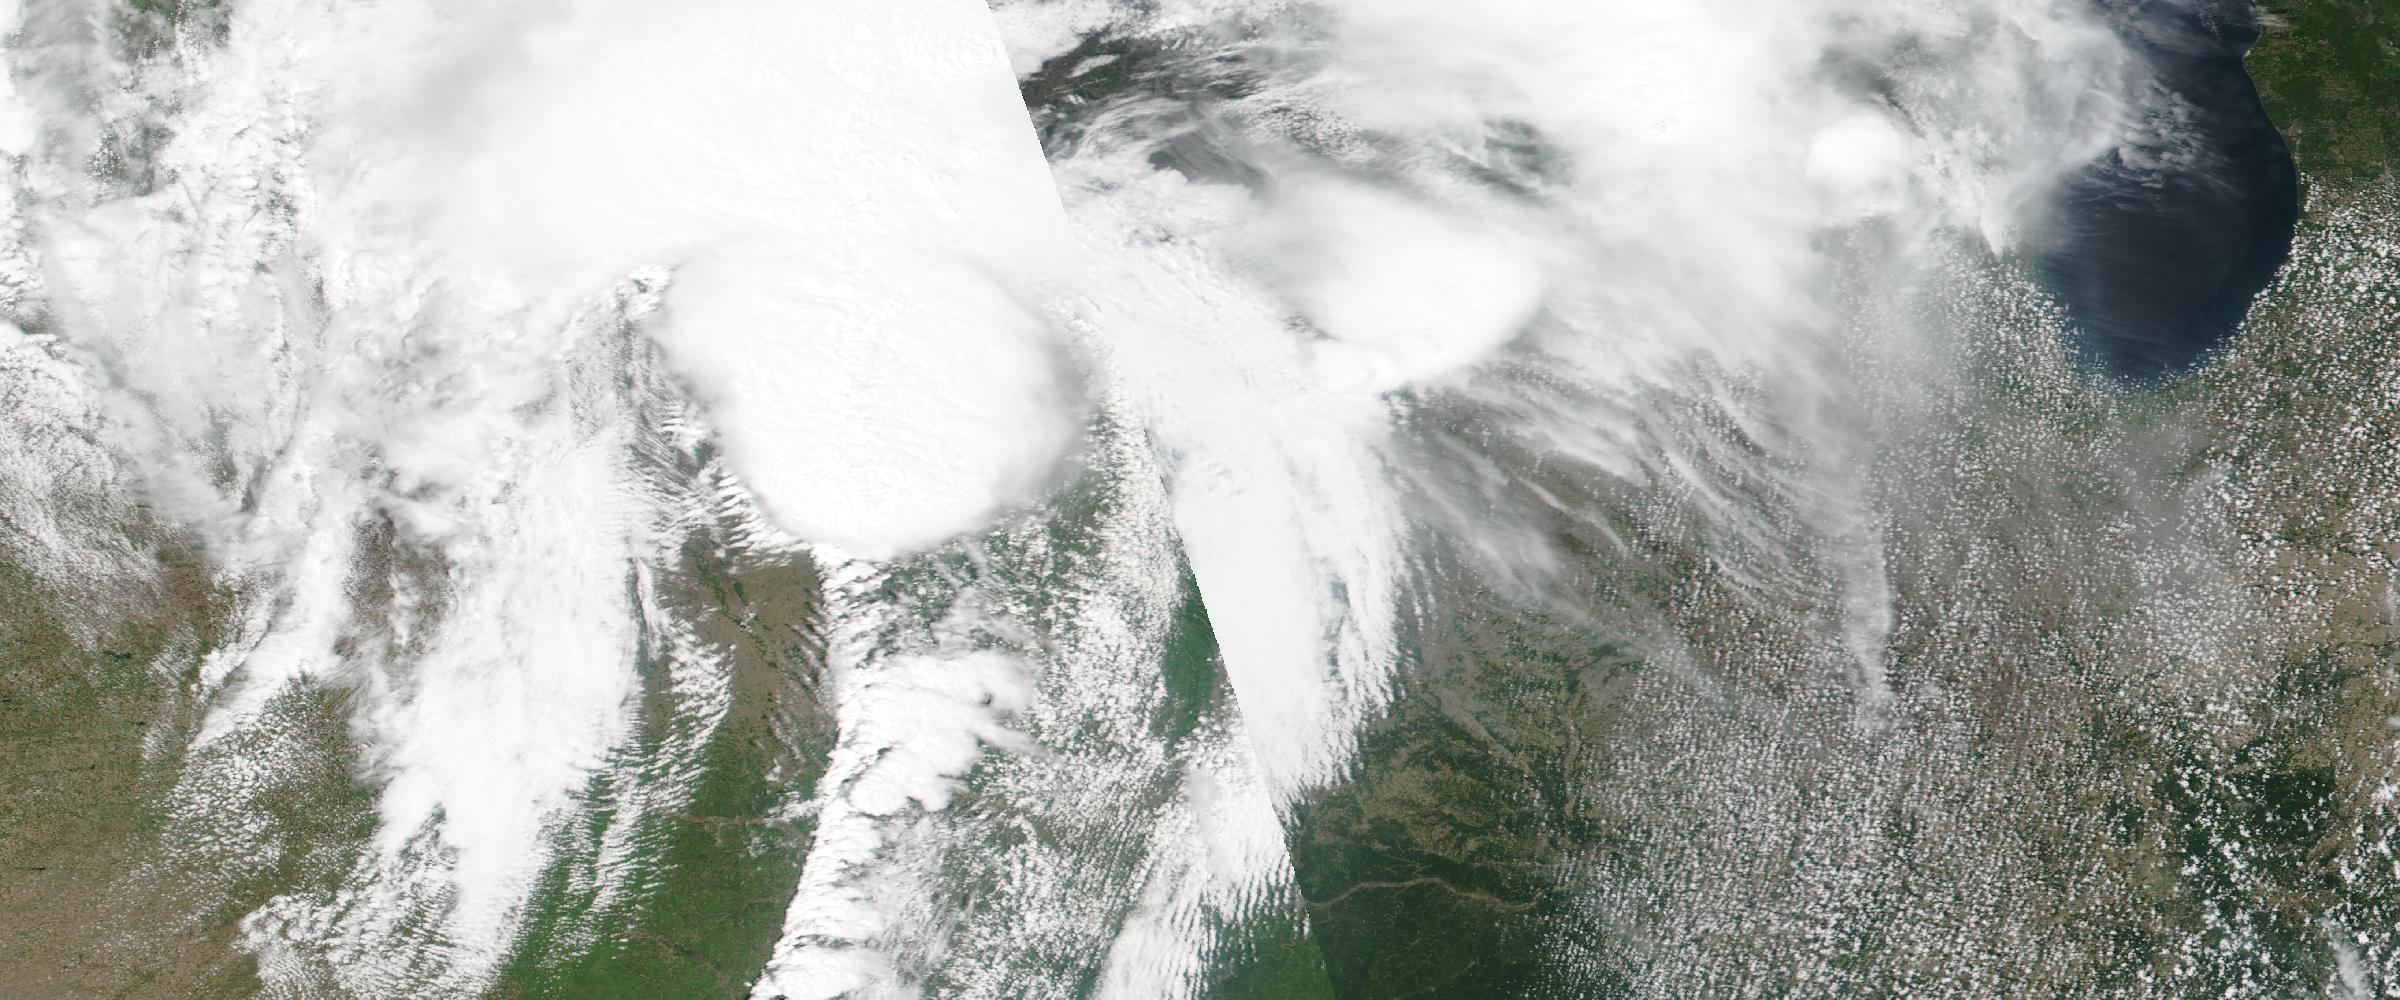
When a tornado moves through a community, insurers can quickly face a difficult question: Which properties were actually affected?
A tornado warning can identify a broad area at risk. Radar can help identify where a storm is moving. Reports and assessments can provide additional evidence after the event. But for insurers managing thousands or millions of properties, turning that information into a reliable understanding of portfolio exposure requires something more precise: event-level tornado intelligence that can be connected to individual locations.
This distinction can make a significant difference during catastrophe response, claims triage, exposure analysis, and post-event assessment.
Tornado warnings are designed to communicate imminent danger to people within a geographic area. They are not intended to determine which insured properties were affected. A warning polygon may encompass many properties that ultimately experience no damage, while the actual tornado path may affect only a small portion of that area.
For an insurer, this creates an important distinction between:
These are not interchangeable measures of exposure. Using the warning area alone can therefore produce a broad estimate of potentially exposed properties without necessarily providing a precise picture of which locations encountered the hazard.
The first step toward understanding tornado exposure is connecting the event to the insurer's own location data. An insurer may have thousands of residential and commercial properties distributed across a region. Each location can contain information such as:
When tornado event intelligence is combined with that information, insurers can begin to identify which locations intersect with the observed event. This transforms a weather event into a portfolio exposure assessment.
Instead of asking:
“How many properties were inside the tornado warning?”
an insurer can ask:
“How many insured properties intersected the observed tornado footprint, and what exposure is associated with those locations?”
That is a substantially more actionable question.
Put tornado tracks next to your insured locations
Historical Event Intelligence delivers tornado events as track geometry with dates, severity and source provenance — ready to intersect with your own portfolio data.
A tornado's observed or estimated footprint can provide a more granular representation of the event than a warning polygon. Depending on the available intelligence, an event footprint can capture information about the tornado's path, timing, geographic extent, and severity. When overlaid with an insurer's portfolio, this information can help identify concentrations of potentially affected properties.
For example, an insurer could determine that:
The exact numbers will vary by event and by the quality and availability of post-event information. The important point is that exposure can become progressively more refined as better event information becomes available.
Following a significant tornado, claims organizations may receive a large volume of notifications from policyholders. Event intelligence can provide another source of information for prioritizing attention.
Properties identified as being within or near an observed tornado footprint could potentially be flagged for additional review. Claims teams can then combine that information with first notice of loss, customer communications, imagery, adjuster reports, and other available evidence.
This does not replace the claims process or establish whether a particular property was damaged. Instead, it can help insurers organize information and focus resources where there is stronger evidence that an insured location was exposed to the event.
One of the potential advantages of event-level intelligence is that insurers don't necessarily have to wait for claims to understand where their portfolio may have been affected. Once a tornado event has been characterized, insurers can intersect the event information with their exposure data and begin assessing potential concentrations.
This can support questions such as:
Having this information early can give catastrophe response teams a more informed starting point while claims information develops.
One of the most important considerations in using hazard intelligence for insurance is avoiding the assumption that geographic exposure automatically means physical damage. A property can be located within a tornado footprint and sustain little or no damage.
Conversely, information about a tornado's path may not capture every location that experiences secondary impacts or damage outside the most clearly defined footprint.
For this reason, tornado intelligence should be viewed as one layer of evidence within the broader claims and catastrophe assessment process. Combining event intelligence with property characteristics, claims data, aerial or satellite imagery, field assessments, and other sources can provide a progressively more complete understanding of loss.
The same event intelligence used during an active catastrophe can also support longer-term portfolio analysis.
Historical tornado data can help insurers investigate questions such as:
Historical event data can therefore become part of underwriting research, portfolio management, catastrophe analytics, and risk accumulation analysis. Instead of treating each tornado as an isolated event, insurers can build a longer-term view of how their portfolios have interacted with severe weather over time.
The evolution of tornado intelligence reflects a broader shift in catastrophe risk management. Warnings remain essential for communicating immediate threats. But insurers have needs that extend beyond the initial warning. They need to understand the event itself.
Answering those questions requires connecting hazard intelligence with location-level exposure data. The result is a more detailed picture of catastrophe exposure—one that can support both immediate response and longer-term portfolio analysis.
For insurers, the value of tornado intelligence is not simply knowing that a tornado occurred. It is understanding where the event intersected with the portfolio and progressively enriching that picture as additional observations and impact information become available.
The workflow can be thought of as a progression:
Detect → Characterize → Map → Intersect → Assess → Verify
Detection identifies the threat. Event characterization describes what happened. Mapping provides geographic context. Portfolio intersection identifies potentially exposed insured locations. Assessment helps prioritize exposure and response. Verification incorporates additional evidence about actual impacts and damage.
No single dataset can answer every question.
But bringing these layers together can help insurers move from broad catastrophe alerts toward a more precise understanding of which properties were actually in the path of an event and what happened to them.
For insurers managing geographically distributed portfolios, that distinction can turn tornado intelligence from an alerting tool into a more useful component of catastrophe response and exposure management.
Explore the historical record
Decades of reconstructed, verified catastrophes — browse the Historical Event Intelligence overview, or request sample data for your own portfolio.
How do insurers determine which properties a tornado affected? By intersecting the event's observed track or footprint with their own location data — coordinates, property type, insured value, coverage and construction attributes. That turns a weather event into a portfolio exposure assessment, replacing “how many properties were inside the warning?” with “which insured locations intersected the observed footprint, and what exposure sits at those locations?”
Does being inside a tornado footprint mean a property was damaged? No. Geographic exposure is not physical damage. A property can sit inside a footprint and sustain little or none, and a track may not capture every location that experiences damage outside the clearly defined area. Tornado intelligence is one layer of evidence, used alongside claims data, imagery, field assessments and property characteristics.
Can insurers assess tornado exposure before claims are filed? Yes. Once an event has been characterized, its footprint can be intersected with exposure data straight away, which shows which policies may have been exposed, what insured value falls inside the footprint and where the concentrations are. That gives catastrophe response teams a starting point while claims information is still developing.








Decision-ready intelligence for understanding what's happening, what is impacted, and what to do next. Global hazard, severe weather, catastrophe, and physical risk intelligence trusted by governments, enterprises, insurers, humanitarian organizations, and technology platforms worldwide.
Request DemoContact Us

